Silver has a dual identity that makes it fundamentally different from gold as an investment: alongside its long history as a monetary and jewelry metal, silver is now, first and foremost, an industrial commodity. Industrial applications account for roughly 60% of total silver consumption, up from 50% just a decade ago, and this shift has profound implications for how the metal behaves in the market. Here is what silver is actually used for, and why industrial demand has become the dominant force shaping its price.
The Short Answer
Silver’s largest and fastest-growing use is industrial — primarily solar panel manufacturing and electronics — which together with other industrial applications now accounts for roughly 60% of global demand. This is a fundamental difference from gold, whose demand is dominated by investment, central bank reserves, and jewelry rather than industrial consumption.
Solar: Silver’s Fastest-Growing Demand Driver
Solar photovoltaic (PV) manufacturing has become silver’s single fastest-growing end market. Every crystalline silicon solar cell uses silver paste to conduct electricity to the panel’s external circuit — the fine metallic lines visible on a panel’s face. According to the Silver Institute’s World Silver Survey 2025, solar PV consumed approximately 232 million troy ounces of silver in 2024, representing roughly 19% of total silver demand and around 34% of all industrial silver consumption — a dramatic increase from a decade earlier when solar’s share was a small fraction of that.
Manufacturers have worked continuously to reduce the amount of silver used per solar cell — a process the industry calls “thrifting” — cutting silver consumption per watt by roughly 15-20% compared to earlier manufacturing techniques. But global solar deployment has grown even faster than thrifting has reduced usage, meaning total silver consumption from solar keeps climbing year after year despite the efficiency gains.
Electronics: The Largest Single Category
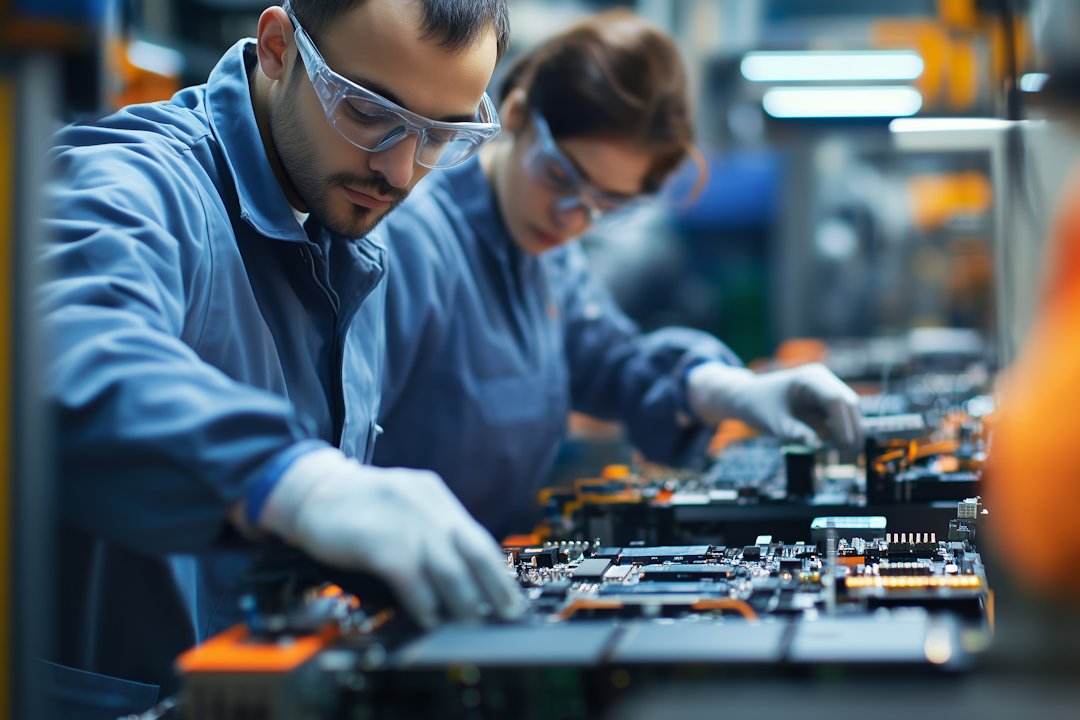
Electrical and electronics applications remain the single largest category of industrial silver demand by volume, estimated at roughly 300 to 310 million ounces in 2026. Silver’s unique combination of the highest electrical and thermal conductivity of any metal makes it essential in circuit boards, switches, connectors, and semiconductors found in virtually every modern electronic device, from smartphones to computers.
A newer and rapidly growing subset of this category is data center infrastructure. As AI computing expands globally, demand for high-speed networking equipment and thermal management systems is rising sharply — AI workloads generate substantially more heat and require more processing power than traditional computing, and silver’s combined electrical and thermal properties make it particularly well suited to managing both challenges simultaneously.
Other Industrial and Medical Applications
Beyond solar and electronics, silver has meaningful applications in electric vehicle production (silver is used in various electrical contacts and components), 5G network infrastructure, and healthcare. Silver’s natural antimicrobial properties make it valuable in wound care products, surgical mesh, and water purification systems — hospital infrastructure investment, which reached an estimated $180 billion globally in 2025, incorporates meaningful silver content through these applications.
The Structural Supply Deficit
Global silver mine production has remained essentially flat at around 830 million ounces annually since 2015, while industrial demand alone is on track to exceed 720 million ounces in 2026 — the highest figure in Silver Institute records. This imbalance has produced a structural market deficit that has now persisted for six consecutive years.
This supply constraint exists partly because silver is often mined as a byproduct of other metals — particularly lead, zinc, and copper — rather than as a primary target on its own, meaning silver mine output doesn’t respond quickly or directly to rising silver prices the way a primary commodity’s supply typically would. Higher silver prices in 2024 and 2025 are beginning to attract new exploration capital, but permitting and construction timelines mean meaningful new supply is unlikely to arrive before 2028 to 2030, according to Minted Metal.
Recycling: A Limited Offset
Silver recycling adds approximately 180 to 190 million ounces annually, primarily from industrial scrap, electronics, and jewelry and silverware. However, recycling volumes have remained essentially flat for five years, and — somewhat counterintuitively — higher prices have not produced the surge in recycling volume that might be expected. The reason is that silver content in most individual scrap items is small, making collection economically marginal even at elevated prices. Solar panel end-of-life recycling is beginning to develop but will not produce meaningful volumes until the 2030s, when panels installed during the 2010s begin reaching the end of their 25-to-30-year operational lifespans.
Why This Matters for Investors
Because industrial demand now drives the majority of silver consumption, silver prices are influenced by a different and, in some ways, more complex set of factors than gold — combining silver’s traditional behavior as a monetary and safe-haven metal with genuine industrial supply-and-demand economics tied to solar deployment, electronics manufacturing, and technology infrastructure buildout. This dual nature is part of why the gold-silver ratio, covered in our earlier explainer, has become such a widely watched tool — it captures the relative pull of these two different demand drivers on the two metals.
Key Takeaways for Investors
- Industrial applications now account for roughly 60% of global silver demand, up from 50% a decade ago
- Solar PV manufacturing is silver’s fastest-growing use, consuming close to 200 million ounces annually and rising despite ongoing efficiency improvements
- Electronics remains the largest single demand category, with AI data center infrastructure emerging as a significant new growth driver
- Global mine supply has been essentially flat since 2015, creating a structural market deficit that has persisted for six consecutive years
- Silver is often mined as a byproduct of lead, zinc, and copper, meaning supply doesn’t respond quickly to rising prices
- New supply from fresh exploration capital is unlikely to arrive in meaningful volume before 2028-2030 given permitting and construction timelines
SOURCES
1. GoldSilver.com — Silver Industrial Demand: Solar, EVs, and the Supply Gap: https://goldsilver.com/industry-news/article/silver-industrial-demand-solar-evs-and-the-supply-gap/
2. SD Bullion — How Much Silver Is Used in Solar Panels?: https://sdbullion.com/blog/how-much-silver-is-used-in-solar-panels
3. Minted Metal — Silver Industrial Demand 2026: Solar and EVs: https://mintedmetal.com/analysis/silver-industrial-demand-2026/
4. GR Reserve — Industrial Uses of Silver: Complete 2026 Guide: https://grreserve.com/learn/silver-industrial-uses-applications-demand/
DISCLAIMER
This article is an educational explainer based on publicly available industry data, market research, and published analyst commentary. Information was current as of the publication date noted below. Commodity price data and forecasts are sourced as cited and reflect market conditions at the time of writing.
Mining Markets Report has not received compensation from any company, institution, or organization in connection with this article.
Institutional price forecasts and analyst commentary referenced in this article represent third-party opinions at the time of publication and are not guarantees of future commodity performance.
The information provided is for informational and educational purposes only and does not constitute financial, investment, or professional advice. Readers are encouraged to conduct their own due diligence and consult a qualified financial advisor before making any investment decision.
For full terms, see our Disclaimer.