Emerita Resources Corp. (TSXV: EMO; OTCQX: EMOTF; FSE: LLJA) reported results from a pre-feasibility study for its wholly owned Iberian Belt West polymetallic project in southwestern Spain.
The study estimates an after-tax net present value of US$776 million at an 8% discount rate, an after-tax internal rate of return of 23.51% and a 21-year mine life.
However, those economics depend heavily on assumed commodity and concentrate prices, while substantial financing, permitting and development work remains outstanding.
Initial Capital Estimated at US$567 Million
Initial capital is estimated at US$566.7 million, including contingency. The study also includes US$279.5 million in sustaining capital and US$12 million in closure costs, bringing projected life-of-mine capital spending to US$858.2 million.
The PFS estimates a payback period of one year and 11 months after production begins. Measured from the initial investment, the projected payback period is six years and 11 months because the development schedule includes five preproduction years.
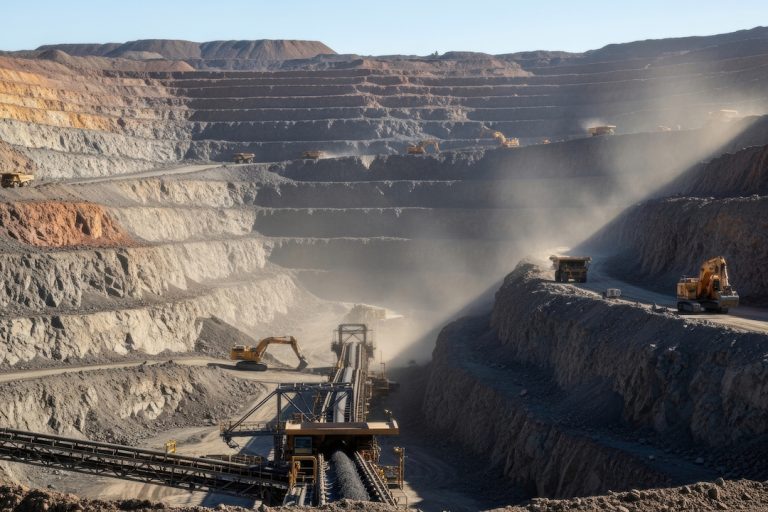
Projected operating costs average US$86.49 per tonne processed. The planned underground operation would use long-hole open stoping to supply a conventional flotation plant with nominal annual capacity of 1.2 million tonnes.
Maiden Reserve Supports 21-Year Plan
The study establishes an initial Probable Mineral Reserve of 23.4 million tonnes grading 2.30% zinc, 1.13% lead, 0.45% copper, 53 grams per tonne silver, 1.07 g/t gold and 33.85% sulphur.
The mine plan draws material from the La Romanera, El Cura and La Infanta deposits. La Romanera would provide most of the plant feed, supplemented by the other two deposits.
An updated resource estimate contains 26.1 million Indicated tonnes and 9.9 million Inferred tonnes. Mineral Resources are inclusive of Mineral Reserves.
Inferred resources were excluded from the economic analysis and treated as waste. There is no certainty that further drilling will convert them into reserves or extend the planned mine life.
Pyrite Concentrate Drives Projected Revenue
The proposed plant would produce zinc, lead, copper and precious-metals-bearing pyrite concentrates.
Between years two and 19, the study projects average annual production of approximately 43,489 tonnes of zinc concentrate, 26,120 tonnes of lead concentrate, 10,633 tonnes of copper concentrate and 694,620 tonnes of pyrite concentrate.
Pyrite concentrate accounts for approximately 66% of the project’s projected net smelter return. Unlike exchange-traded metals, its price would be negotiated through commercial sales or offtake agreements.
The base case assumes a pyrite concentrate price of US$274 per tonne, with gold and silver credits calculated separately. Emerita has not executed any concentrate offtake, hedging or forward-sales agreements for the project.
Economics Depend on Price Assumptions
The base case uses long-term prices of US$5.20 per pound for copper, US$1.35 per pound for zinc, US$0.93 per pound for lead, US$3,750 per ounce for gold and US$52 per ounce for silver.
Changes in those assumptions, particularly the price and commercial terms for pyrite concentrate, could materially affect the projected NPV and IRR.
Emerita has started the environmental permitting process and said Iberian Belt West has received strategic-project status from the regional government of Andalusia. That designation does not guarantee approvals or establish a development timeline.
The project still requires additional engineering, permits, financing, construction and negotiated concentrate-sale agreements. The PFS does not constitute a construction decision or guarantee that the projected economics will be achieved.
Sources
- Emerita Announces Positive Iberian Belt West Pre-Feasibility Study Results — Oct. 29, 2026
- Emerita Resources Provides Update on Preliminary Feasibility Study — Sept. 30, 2026
- Emerita Resources — Iberian Belt West Project
Editorial Disclosure
This article was prepared from publicly available company disclosures and related technical information. Mining Markets Report received no compensation from Emerita Resources Corp. for its preparation or publication and has no disclosed business relationship with the company.
The author and publisher do not hold securities in Emerita Resources Corp. The economic results discussed in this article are company estimates from a pre-feasibility study and have not been independently verified by Mining Markets Report.
Projected NPV, IRR, costs, production, recoveries, mine life and payback depend on commodity prices, pyrite-concentrate pricing, metallurgical performance, permitting, financing and other assumptions. Emerita has not executed concentrate offtake agreements, and a construction decision has not been announced.
This article is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell securities. Mining investments can be highly speculative. Readers should conduct their own due diligence and consult a qualified financial professional. Read the full Mining Markets Report disclaimer.