Highlights
- Copper on the London Metal Exchange notched a string of record highs through early September 2026, extending a 10-week winning streak, its longest since 1994, before easing back from the peak.
- Chile, the world’s largest copper producer, posted its weakest second-quarter output in roughly 19 years and has cut its 2026 production forecast for a second straight quarter, to a projected 2.6% annual decline.
- Morgan Stanley began the year forecasting mine-supply growth. It now expects global output to come in flat to lower for 2026, which would mark the first annual decline since 2017.
Copper doesn’t usually string together ten weekly gains in a row. It did this year, and the reason has little to do with a sudden jump in demand. It has to do with the ground underneath one country.
Chile’s Slump
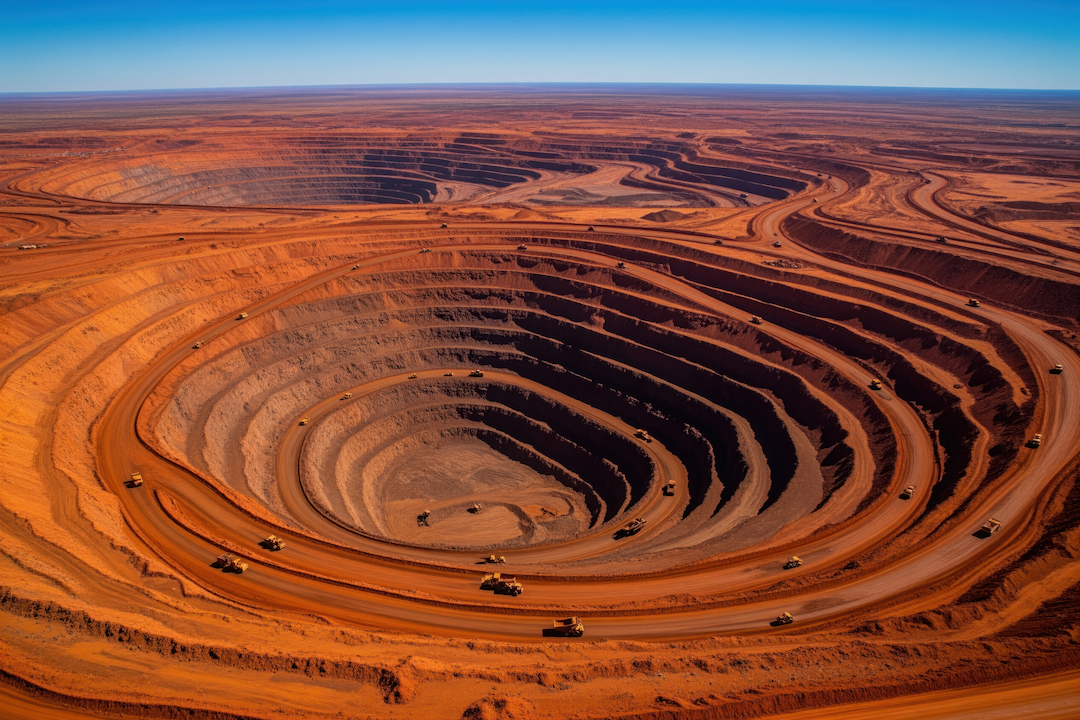
Chile mines more copper than anywhere else on earth, and lately it isn’t mining much of it. The country posted its weakest second-quarter output in roughly 19 years, and Chile’s state copper commission, Cochilco, has trimmed its full-year 2026 forecast twice in a row, most recently landing on a 2.6% annual decline. Aging mines, falling ore grades, and a run of operational setbacks at flagship operations are doing the damage, not any single event.
That matters well beyond Chile’s borders. The country accounts for roughly a quarter of the world’s mined copper, and there’s no easy substitute sitting in reserve when its output slips.
A Global Pattern, Not Just a Local One
Other producing countries are seeing versions of the same story this year; Chile’s is simply the largest example. Global mine production fell 1.1% in the first half of 2026. Morgan Stanley began the year forecasting supply growth and has since revised that down to flat-to-lower for the full year. If that holds, it would mark the first annual decline in global copper mine output since 2017.
Prices have moved the way that backdrop would suggest. LME three-month copper touched fresh records through the first half of September before easing back into the mid-$14,000s per tonne as warehouse stocks ticked higher and traders weighed the timing of the next Federal Reserve rate move. The pullback doesn’t undo the underlying story. It’s a reminder that a tight physical market and a jumpy paper market can move on different clocks.
Why the Supply Response Is Slow
A record price is normally an invitation for miners to dig more. Copper isn’t cooperating this time. Bringing a new deposit into production typically takes a decade or more from discovery, and the deposits still being found tend to run deeper, grade lower, and sit in jurisdictions where permitting and community relations add years rather than months. A high price can fund more exploration. It can’t shorten a geological timeline.
The Financing Gap Beneath the Story
That timeline creates a problem money alone doesn’t solve. Building a copper mine now routinely costs well over a billion dollars, and most companies holding undeveloped deposits are small exploration outfits nowhere close to that kind of balance sheet. Three structures have become the common workarounds: royalty and streaming deals, which sell forward a slice of future production for cash today; earn-in agreements, which trade project equity for exploration spending; and carried interests, where a larger, better-funded partner covers construction in exchange for control of the schedule and the budget. Each shifts a different piece of the risk to a different party, and each caps a different slice of the eventual upside.
None of that changes the arithmetic on the supply side. It only determines who ends up funding, and who ends up controlling, the projects that eventually close the gap.
Sources
- Bloomberg: Copper Price Record High: How Tariff Fears Are Driving a Supply Squeeze, September 8, 2026
- Discovery Alert: Chile’s Copper Crisis Deepens as Codelco Drops 1.7Mt Target, citing Cochilco production data, September 2026
- OilPrice.com: Copper’s Longest Rally Since 1994 Collides With a Shrinking Supply Chain
- iTiger News: Global Copper Mine Output Poised for First Annual Drop Since 2017, Bolstering Price Outlook, citing ICSG and Morgan Stanley data
- Discovery Alert: LME Copper Prices Retreat From Record as Stocks Rise and Fed Looms, September 2026
Editorial Disclosure
This article is based on copper market pricing data, Chilean government production figures reported via Cochilco, and third-party analyst commentary reported by Bloomberg, OilPrice.com, and other financial media outlets, current as of September 2026 and cited in the Sources section above. Mining Markets Report was not compensated for this coverage and holds no financial interest in any company, commodity position, or security referenced or implied by this article. Statements regarding future copper production, prices, or supply-and-demand balances are forward-looking and involve risks and uncertainties; actual results may differ materially. This is not investment advice.
For further details regarding our editorial independence, publishing policies, and full risk disclaimers, please see our full Terms & Disclaimers Page