Highlights
- Mordor Intelligence projects global lithium carbonate volumes rising from 1.41 million LCE tons in 2026 to 3.93 million LCE tons by 2031, about 22.7% a year.
- Benchmark Mineral Intelligence assessed battery-grade lithium carbonate at $19,750 per tonne (CIF Asia) on September 2, 2026.
- The forecast comes from a paid commercial report promoted by press release; its methodology is not public and has not been independently verified.
Lithium carbonate demand could nearly triple in five years. That’s the pitch from Mordor Intelligence, a Hyderabad-based market research firm that promoted its new lithium carbonate report in a September 28, 2026, press release distributed via PRNewswire.
The firm projects global volumes climbing from 1.41 million tons of lithium carbonate equivalent (LCE) in 2026 to 3.93 million tons by 2031. LCE is the industry’s common yardstick, converting different lithium chemicals into one comparable unit. Mordor puts the growth rate at 22.74% a year. We ran its start and end figures ourselves and got about 22.7%, so the math holds.
Treat it as one vendor’s view. The release is marketing for a paid report, and the methodology behind the numbers isn’t public.
Why Carbonate Matters
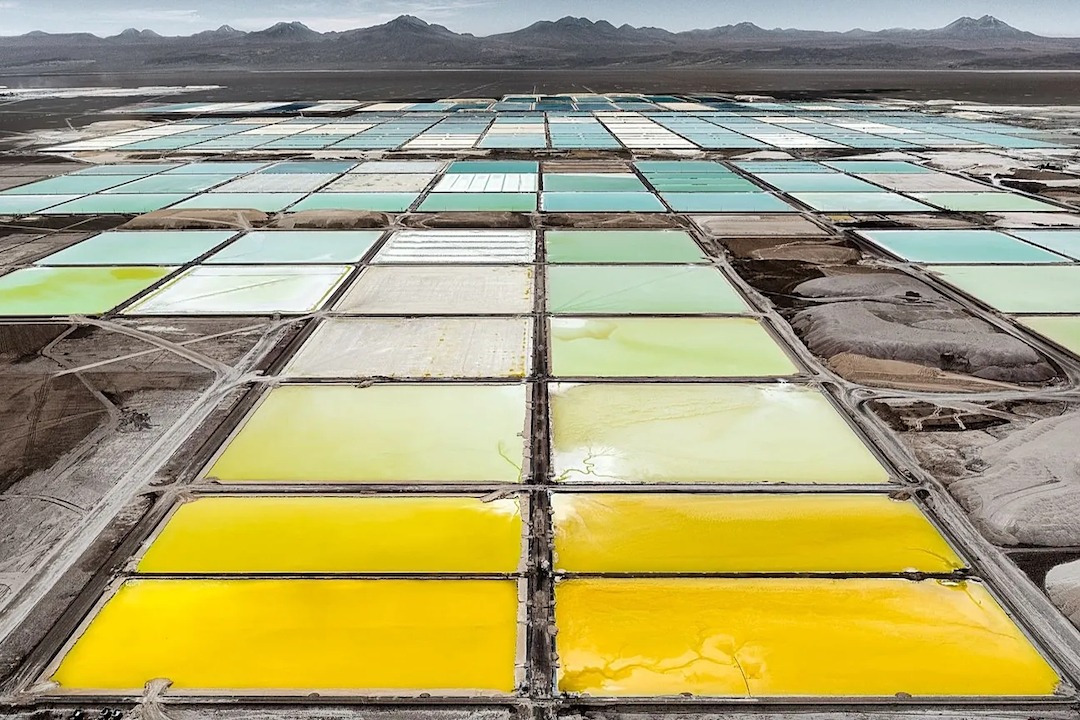
Lithium reaches battery makers in two main chemical forms. Hydroxide has long been the choice for high-nickel EV cells. Carbonate feeds lithium iron phosphate, or LFP, batteries, which are cheaper, last longer and now dominate grid storage. Mordor ties its forecast to exactly that shift.
Storage has hard numbers behind it. U.S. installations hit a record 57.6 GWh in 2025, up 30% from 2024, according to the Solar Energy Industries Association (SEIA) and Benchmark Mineral Intelligence. SEIA projects about 70 GWh for 2026. The first half delivered 30.8 GWh.
Mordor’s release muddles this. It presents 57.6 GWh as an expected 2025 utility-scale figure and suggests installs could triple in 2026. The number is now a reported total across all segments, and SEIA’s own projection implies growth of roughly a fifth this year, not a tripling.
Where Prices Stand
Volume forecasts say nothing about price. Price is what miners live on.
Benchmark assessed battery-grade carbonate at $19,750 per tonne on September 2, 2026, on a CIF Asia basis, meaning delivered to North Asian ports. Intratec put the global battery-grade average near $11,000 in November 2025. The two benchmarks aren’t identical, but that’s a gain of roughly 80% in under a year.
September got choppier. Mysteel reported Chinese battery-grade carbonate sliding from RMB 133,800 to RMB 130,300 per tonne between September 14 and 16, including a single-day drop of RMB 3,750. Mordor itself lists price swings as a risk to producer margins and planning.
The Refining Bottleneck
Mining lithium is one step. Turning it into battery-grade chemicals is another, and China controls most of it. The International Energy Agency (IEA) estimates China produces about 70% of the world’s lithium chemicals, and its 2025 outlook still has China supplying more than 60% of refined lithium in 2035. Mordor’s 60% to 70% refining estimate fits that range.
The release points to new capacity in Nevada. The most advanced example is Thacker Pass, where Lithium Americas (TSX: LAC; NYSE: LAC) is building a clay-hosted project designed for 80,000 tonnes a year of battery-grade carbonate across two phases. The company’s latest quarterly filing targets mechanical completion of Phase 1 in late 2027.
Check the Policy Fine Print
The release cites two U.S. incentives: $35 per kWh for domestically made battery cells, and a 10% critical-minerals credit. Both come from the Section 45X manufacturing credit created under the Inflation Reduction Act.
What the release leaves out is that the One Big Beautiful Bill Act, signed July 4, 2025, amended 45X. Under current law, battery component credits begin phasing down in 2030. The critical-minerals credit, previously open-ended, now phases out between 2031 and 2034. Foreign-entity-of-concern rules also add sourcing restrictions.
Reading the Forecast
Research-firm forecasts are commercial products. They aren’t peer-reviewed, and different vendors routinely publish very different numbers for the same market.
Hitting that figure would take a large build-out of mines and refineries. The firm flags the same hurdles: lengthy approvals, technical requirements and skilled-labor shortages outside China.
Demand looks durable. Whether supply keeps pace, and at what price, is the real question for producers from Albemarle and SQM to Pilbara Minerals.
Sources
- Mordor Intelligence: Lithium Carbonate Market to Register 22.74% CAGR Through 2031 as EV Battery Demand Accelerates, PRNewswire, September 28, 2026
- SEIA: U.S. Adds 58 GWh of New Energy Storage Capacity in 2025, Largest Single Year of New Battery Capacity on Record, February 2026
- pv magazine USA: U.S. Energy Storage Shatters Records with 58 GWh Installed in 2025, February 23, 2026
- Benchmark Mineral Intelligence: Lithium Prices
- Intratec: Lithium Carbonate Price, Historical and Current
- Mysteel: China Lithium Market Prices, Data and News
- Mercom India: China’s Dominance in Critical Minerals Supply and Refining Continues: IEA, May 27, 2025
- IEA: Global Critical Minerals Outlook 2025, Overview of Outlook for Key Minerals
- Lithium Americas Corp.: Form 10-Q for the Quarter Ended June 30, 2026, SEC EDGAR
- Mining Weekly: Thacker Pass Lithium Project, US, Update, May 22, 2026
- Congressional Research Service: The Section 45X Advanced Manufacturing Production Credit
- Stephano Slack: Advanced Manufacturing Production Credit, 2025 Updates and Strategic Insights, July 8, 2025
Editorial Disclosure
This article is based on a press release issued by Mordor Intelligence Private Limited on September 28, 2026, and distributed via PRNewswire, supplemented by independently sourced market data listed in the Sources section. The release promotes Mordor Intelligence’s own paid research report. All forecast figures attributed to Mordor Intelligence reflect a commercial, paid-methodology projection and have not been independently verified by Mining Markets Report. Securities discussed: none directly. Lithium Americas Corp. (TSX: LAC | NYSE: LAC) and the producers named in this article appear for industry context only. Mining Markets Report has not received compensation from Mordor Intelligence, any company named in this article, their management, investor relations representatives, or any third party for the creation of this specific coverage. No staff member, principal, or affiliate of Mining Markets Report holds a position, option, or interest in any security named as of the publication date. References to U.S. tax legislation describe enacted provisions only; no policy opinion is offered. Market forecasts, price trends, project timelines, and policy outcomes described here are forward-looking statements. They are subject to market, operational, regulatory, and policy risks; actual outcomes may differ materially. Commodity markets and mining equities carry a high degree of financial risk, and lithium prices in particular have been highly volatile. This overview is published strictly for informational, news-reporting, and educational market context purposes only. It does not constitute an investment recommendation, endorsement, or professional financial, legal, or tax advice.
For further details regarding our editorial independence, publishing policies, and full risk disclaimers, please see our full Terms & Disclaimers Page