Aclara Resources Inc. (TSX: ARA) has reported an updated preliminary economic assessment for the Penco heavy rare earths project in Chile’s Biobío region.
The study estimates an after-tax net present value of US$343.9 million at an 8% discount rate, an after-tax internal rate of return of 26.1% and a 3.2-year payback period.
Penco is being developed through REE Uno SpA, in which Chilean mining and industrial group CAP S.A. holds a 20% interest. The reported economic figures are project-level estimates and should not be interpreted as being wholly attributable to Aclara.
Higher Costs Accompany Improved Economics
The updated PEA estimates construction capital of US$204.4 million, plus US$39.1 million in contingency, bringing total construction capital to approximately US$243.5 million. Sustaining capital is estimated at an additional US$62.3 million.
Total construction capital increased by approximately US$115 million from the 2021 PEA. Aclara attributed the increase to a more detailed process design, updated equipment quotations, additional environmental measures and general cost inflation.
Estimated operating costs also increased to US$28.90 per tonne processed from US$13.60 in the earlier assessment.
Aclara compared the new US$344 million after-tax NPV with US$178 million in the 2021 PEA. However, the two figures are not directly comparable because the studies use different discount rates, resource volumes, designs and rare-earth price assumptions.
Penco Models 17 Years of Production
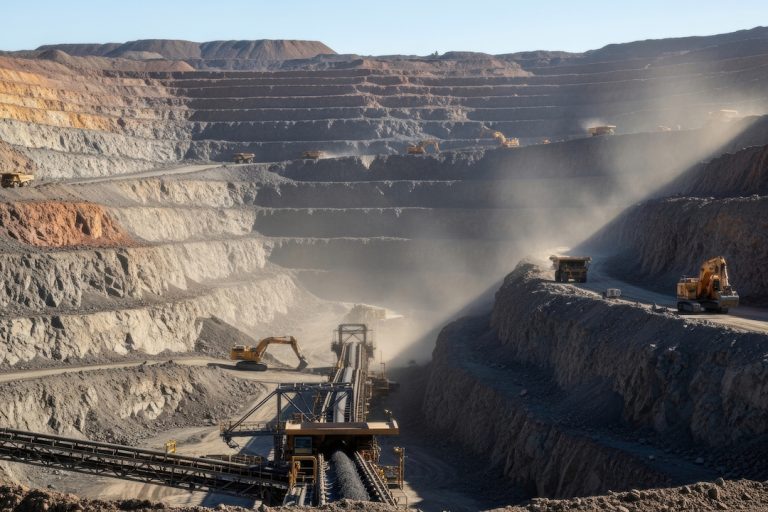
The PEA outlines a 17-year operation processing 30.8 million tonnes of material and producing an average of 732 tonnes of contained rare earth oxides annually, excluding the initial ramp-up and final ramp-down years.
The projected annual output includes approximately 44 tonnes of dysprosium, six tonnes of terbium, 400 tonnes of yttrium and 128 tonnes of combined neodymium and praseodymium.
Aclara expects to produce the oxides within a mixed rare earth carbonate product with 98.9% purity. The company’s model estimates average annual net revenue of US$155 million and EBITDA of approximately US$101 million. These projections are not the same as net income or free cash flow.
Resource Estimate Uses Existing Drill Data
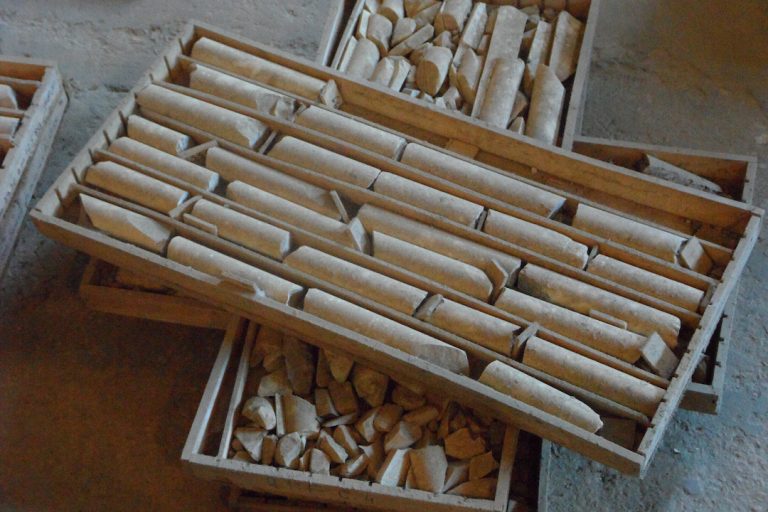
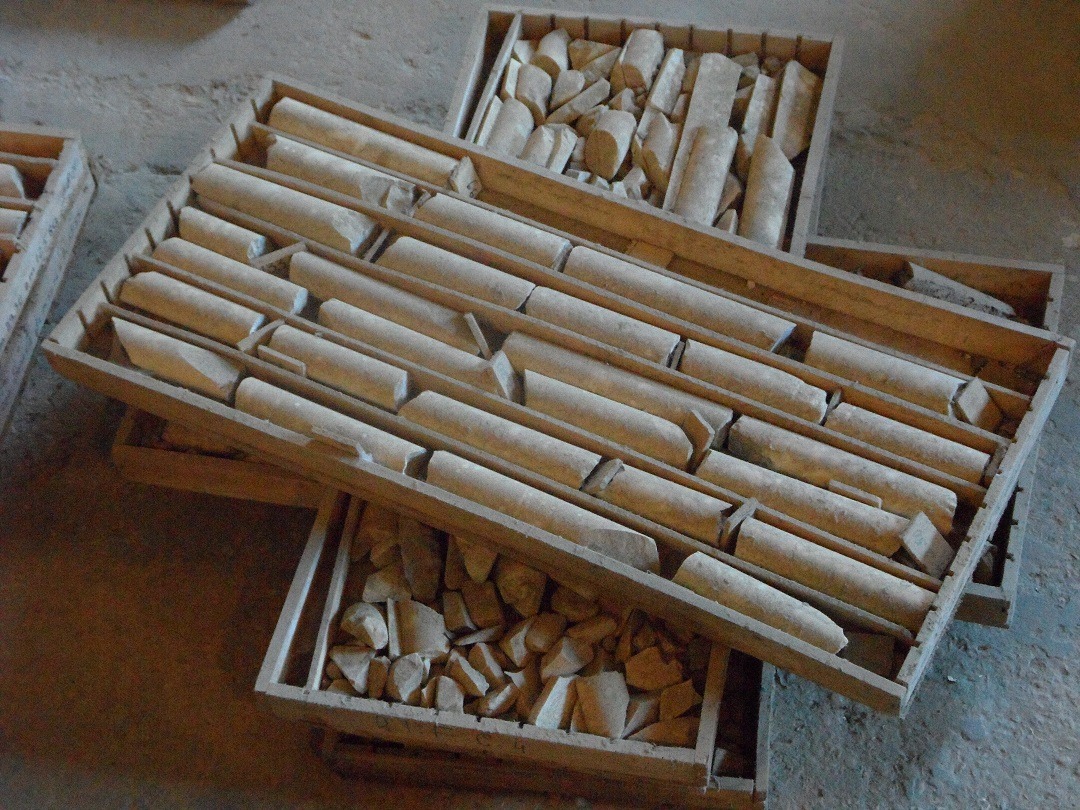
The updated estimate contains 35.8 million tonnes of Measured and Indicated Mineral Resources grading 2,095 parts per million total rare earth oxides. That total includes 26.4 million tonnes classified as Measured and 9.4 million tonnes as Indicated.
Penco also contains 2.2 million tonnes of Inferred Resources grading 1,768 ppm total rare earth oxides.
The underlying drilling database and estimated block grades remain unchanged from the 2022 estimate. The update applies a revised classification method and should not be treated as a new drilling-led resource discovery.
Price and Permitting Risks Remain
The base-case economics use rare-earth price forecasts prepared by Argus Media for markets outside China, with flat prices applied to yttrium and gadolinium. Aclara also disclosed a higher US$1.1 billion after-tax NPV using uncapped forecasts, but that scenario carries greater exposure to price assumptions.
China’s ability to influence rare-earth supply and pricing remains a material commercial risk.
Penco received environmental approval for its initial extraction and processing areas, which support approximately the first 5.5 years of the proposed mine plan. The remaining extraction and deposition areas would require a separate second-stage environmental assessment.
The PEA is preliminary and includes Inferred Resources. Penco does not have Mineral Reserves, and there is no certainty that the projected economics, production rates or development schedule will be achieved.
Sources
- Aclara Updates Penco Module Preliminary Economic Assessment
- Aclara — Penco Module Project Overview
- Aclara Receives Environmental Qualification Resolution for Penco
Editorial Disclosure
This article was prepared from publicly available company and technical disclosures. Mining Markets Report received no compensation from Aclara Resources Inc. for its preparation or publication and has no disclosed business relationship with the company.
The author and publisher do not hold securities in Aclara Resources Inc. The economic estimates, production forecasts, development plans and technical assumptions discussed above were supplied by the company and have not been independently verified by Mining Markets Report.
The PEA is preliminary, includes Inferred Mineral Resources and depends materially on forecast rare-earth prices, operating assumptions, permitting, financing and project execution. Mineral Resources that are not Mineral Reserves do not have demonstrated economic viability.
This article is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell securities. Mining and development-stage investments can be highly speculative. Readers should conduct their own due diligence and consult a qualified financial professional. Read the full Mining Markets Report disclaimer.